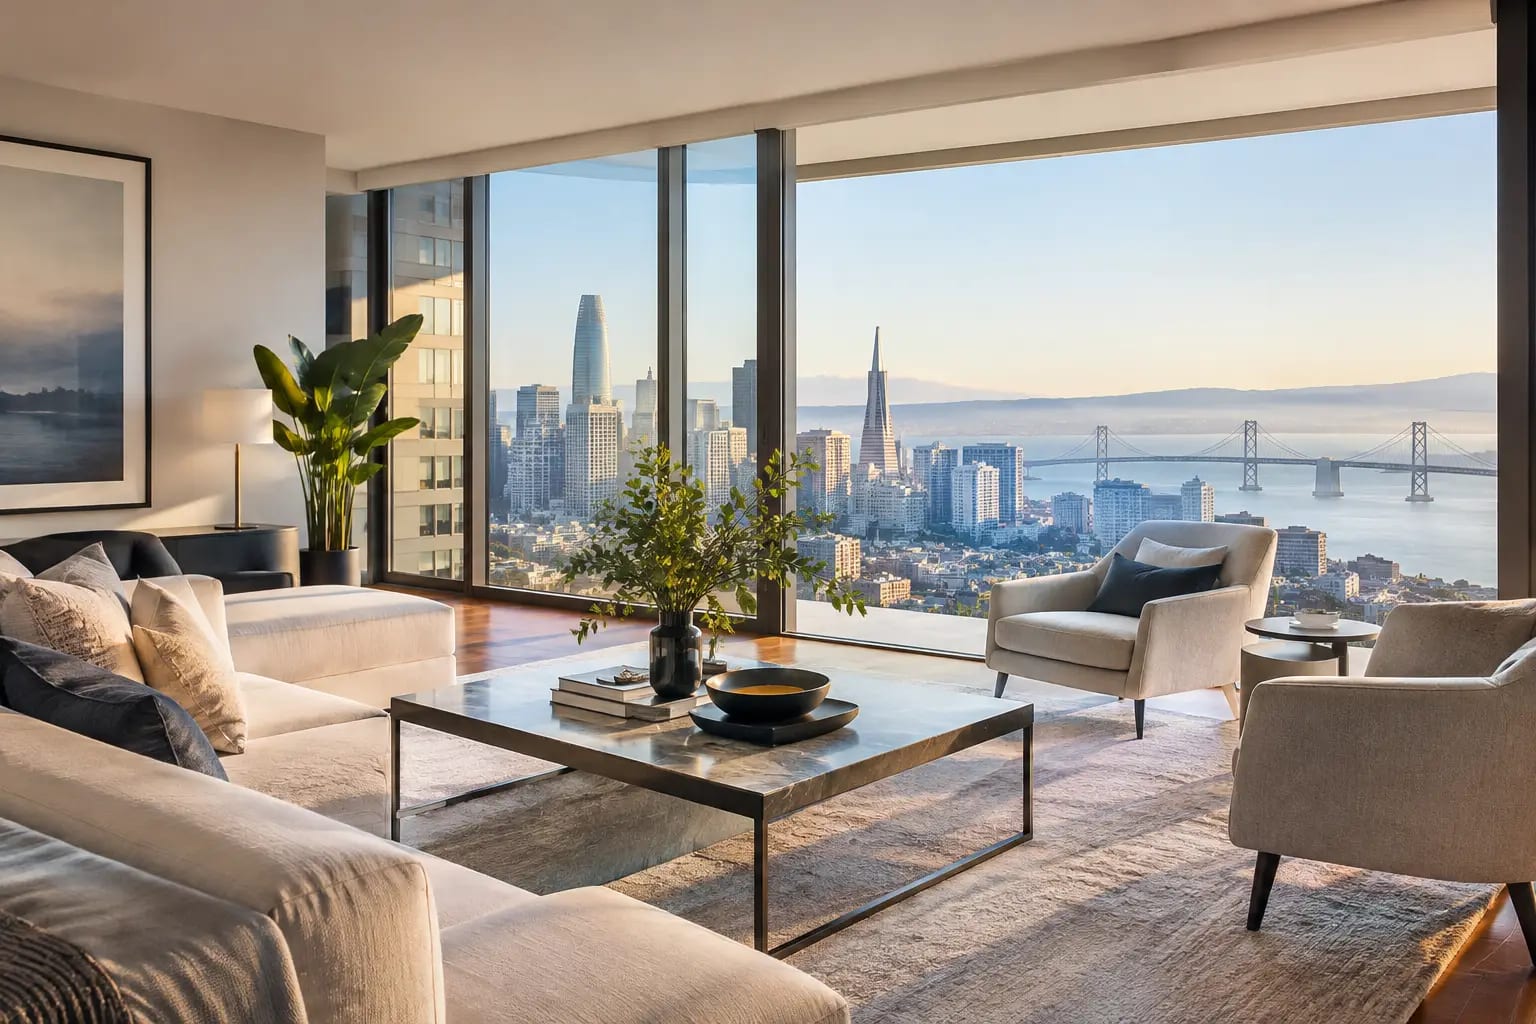

A San Francisco condo can offer a rare combination of location, manageable upkeep, and access to the city’s most established neighborhoods. It can also come with variables that do not appear in a single-family home search: HOA financial health, special assessment exposure, rental restrictions, insurance costs, and the practical realities of shared living. The right purchase is not simply the unit with the best view or newest kitchen. It is the property that supports your lifestyle, budget, and longer-term plans.
For professionals, first-time buyers, investors, and households moving within the Bay Area, buying a condo requires a more complete form of due diligence. Price matters, but the building behind the price often matters just as much.
Start With the Life You Want the Condo to Support
Before comparing square footage, clarify what the property needs to do for you over the next several years. A buyer who expects to commute south on a regular basis may prioritize freeway access and parking differently from someone who wants to walk to the waterfront, work from home, or be close to a particular school or cultural district.
In San Francisco, neighborhood fit can change dramatically within a few blocks. A quiet Pacific Heights side street, a full-service South Beach tower, a Marina District building near shops and restaurants, and a SOMA loft each create a different daily rhythm. Consider how you will use the neighborhood on an ordinary Tuesday, not only on a sunny weekend visit. Test the walk to groceries, assess transit or driving routes at the times you would actually travel, and pay attention to noise, wind, activity, and street conditions.
The unit itself should also be evaluated in light of your likely timeline. A one-bedroom may be an efficient choice for a single professional or a pied-à-terre, while a two-bedroom can provide flexibility for a home office, visiting family, or a future household change. Buying more space than you need can be sensible when the building, layout, and carrying costs support it. It is less sensible when it forces compromises in location, reserves, or financial flexibility.
Evaluate the Building, Not Just the Unit
The central distinction in a condo purchase is that you are buying into a shared financial and operational structure. The homeowner association manages common areas, enforces governing documents, collects dues, and makes decisions that can affect costs and resale appeal.
A strong HOA is not necessarily one with the lowest monthly dues. Very low dues can indicate deferred maintenance or insufficient reserve funding. Higher dues can be appropriate in a full-service building with staffing, elevators, amenities, significant insurance, and substantial maintenance needs. The question is whether the budget is realistic for the building and whether the services provided align with your priorities.
Request and review the HOA document package early. This typically includes the budget, financial statements, reserve study if available, meeting minutes, insurance information, governing documents, and disclosures related to pending or anticipated work. Board meeting minutes are particularly valuable because they often reveal concerns that are not obvious in a listing description: elevator modernization, water intrusion, plumbing projects, façade repairs, litigation, noise complaints, or discussions of a future assessment.
Questions worth answering before you write an offer
Look closely at reserve balances relative to the age and complexity of the building. A newer low-rise building may have different needs than a historic property, a converted warehouse, or a high-rise with elevators and extensive mechanical systems. There is no single reserve number that makes a building automatically sound, but the financial picture should make sense alongside its known capital needs.
Also ask whether assessments have been levied recently or are being discussed. A special assessment is not automatically a reason to walk away. In some cases, it funds a necessary project that improves the building’s condition and protects long-term value. The key is understanding the amount, payment schedule, scope of work, and whether other deferred issues remain.
Insurance deserves the same attention. Building insurance costs and coverage terms have become more consequential for many associations. Review deductibles, coverage limits, claims history, and any pending renewal concerns. Your lender may also have requirements that affect financing, especially when a building faces litigation, has a high concentration of rentals, or does not meet conventional project eligibility standards.
Understand Monthly Costs as a Full Picture
Your purchase price is only one component of ownership. For San Francisco condos, calculate the monthly cost using principal and interest, property taxes, HOA dues, homeowner insurance, parking expenses where applicable, and a reasonable allowance for utilities and personal maintenance.
HOA dues can rise. Property taxes can change after purchase. In a building with older infrastructure, future capital expenses remain possible even with responsible management. Buyers should leave room in their financial plan for ordinary increases rather than qualifying only at the outer edge of comfort.
This is especially relevant for buyers comparing a condo with a single-family home farther from the city. A house may have no HOA dues, but it assigns every repair, exterior project, and insurance decision directly to the owner. A condo distributes certain responsibilities and costs across the building. Neither structure is universally better. The right choice depends on how much control, maintenance responsibility, location access, and predictability you want.
Match the Property Type to Your Priorities
San Francisco’s condo inventory is diverse. The category includes boutique buildings, classic Edwardian flats, converted lofts, contemporary mid-rises, and amenity-rich towers. Each comes with a different ownership experience.
A smaller building may offer lower overhead, a residential feel, and fewer neighbors, but it may also have less professional management and fewer owners to share a major repair. A larger building may provide a concierge, gym, package handling, and structured management, while carrying higher dues and more formal rules. Neither should be judged by size alone.
Parking is another decision that should be made with precision. Dedicated parking can materially improve daily convenience and buyer appeal in some locations. In highly walkable areas or for households that do not keep a car, paying a significant premium for a space may not be necessary. Confirm whether parking is deeded, leased, assigned, or subject to separate rules. The distinction can affect value, financing, and resale.
For investors, rental policies deserve careful review. Some associations limit leasing terms, impose move-in fees, cap rentals, or require board notification. City regulations and building rules can also affect short-term rental plans. If income potential is central to the acquisition, verify the details before relying on projected rent.
Prepare an Offer That Reflects Both Value and Risk
A competitive offer is more persuasive when it is supported by clear judgment. It should account for comparable sales, active competition, the unit’s condition, the building’s financial profile, and the seller’s likely priorities. In a multiple-offer situation, price is important, but financing strength, contingency structure, timing, and the credibility of the buyer can also affect the outcome.
Do not treat all disclosure packages alike. A renovated unit in a financially stable building may justify a more streamlined approach than a property with incomplete records, notable reserve concerns, or unresolved building issues. The goal is not to add contingencies reflexively or waive them casually. It is to understand what you know, what remains uncertain, and how that uncertainty should affect terms.
For cash buyers and buyers with substantial liquidity, the temptation can be to move quickly. Speed can be an advantage, but it should not replace review of the HOA and property disclosures. For financed buyers, early lender coordination is equally important. A preapproval is helpful; an experienced lender who can assess the specific building is better.
Think Beyond the First Year of Ownership
The most successful condo purchases tend to be those that hold up after the excitement of closing. Consider how the property may perform if you need to sell, lease it under permitted rules, or remain there through a professional or family transition. Desirable location, functional layout, natural light, sound building management, and sensible monthly costs often matter more over time than a single dramatic feature.
That does not mean every purchase needs to be optimized solely for resale. A home should serve the person living in it. But a clear view of future marketability provides useful protection in a city where career moves, family needs, and market cycles can change plans.
A thoughtful advisor can help separate a compelling opportunity from a costly compromise. At Parc Bay Real Estate, that process starts with the questions behind the search: how you live now, what may change next, and which trade-offs are genuinely worth making. The right condo should feel considered long after the offer is accepted.