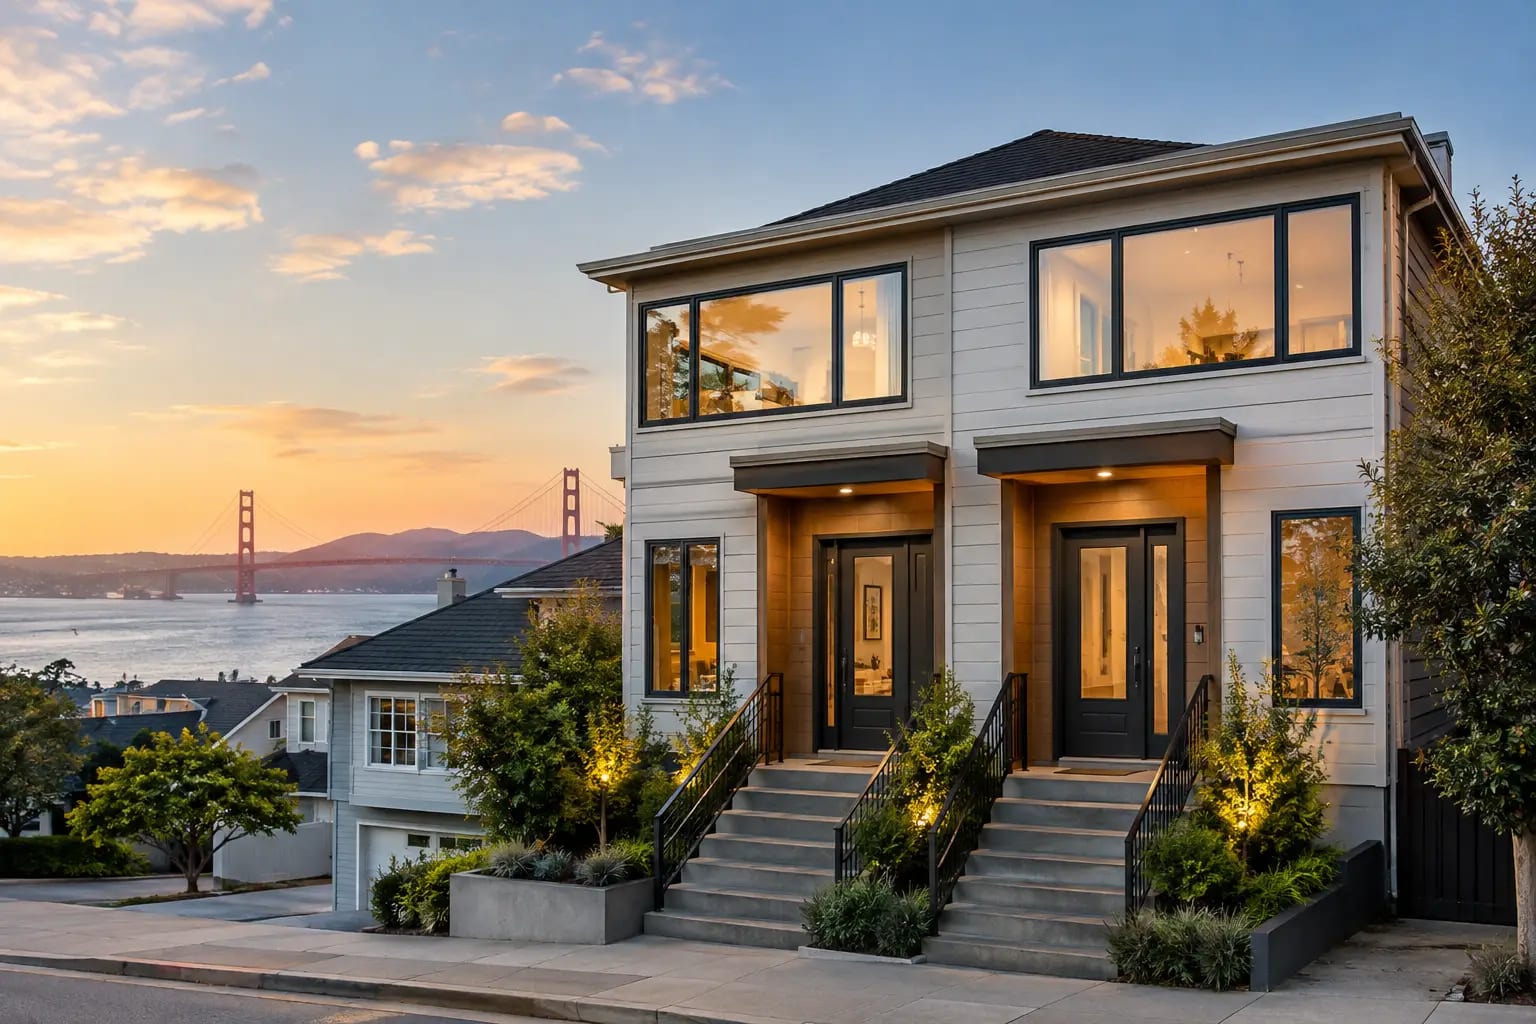

A Bay Area duplex can look like the rarest kind of opportunity: rental income from one unit, flexibility from the other, and a foothold in a market where well-located land has long been scarce. But Bay Area duplex investment properties should not be evaluated as a simple two-rent equation. Existing tenancies, local rent regulations, deferred maintenance, financing terms, and the premium paid for a desirable neighborhood can change the investment case quickly.
For the right buyer, a duplex can be an intelligent way to build a portfolio, offset housing costs, or create future flexibility for family members. The strongest decisions begin with a disciplined view of income, expenses, and the property’s realistic options after closing.
Why duplexes appeal to Bay Area investors
A duplex sits in a useful middle ground. It can offer more income diversity than a single-family rental without the operational scale of a larger apartment building. If one unit is vacant, the second unit may still produce income. An owner-occupant may live in one unit while leasing the other, reducing the effective cost of ownership and gaining familiarity with rental operations before taking on a larger investment.
Flexibility is often the real value. A unit may eventually serve an aging parent, an adult child returning to the area, a relocated employee, or a future owner-occupancy plan. In communities with high barriers to entry, that optionality can matter as much as the first year’s cash flow.
That said, duplexes in San Francisco, the Peninsula, and Silicon Valley often trade at prices that reflect both investment value and homeowner demand. A buyer who assumes the property must meet an aggressive yield target on day one may pass on every viable opportunity. Conversely, a buyer who ignores income fundamentals because the address is desirable can overpay for a difficult-to-manage asset. The right balance depends on the buyer’s time horizon, liquidity, and intended use.
Start with the investment strategy
Before evaluating listings, decide what the duplex needs to accomplish. A long-term investor seeking durable income will analyze the property differently from a buyer who wants to occupy one unit for five years and rent the other.
Owner-occupancy can change the math
Owner-occupants may have access to residential financing options that differ from those available for a purely investment-oriented purchase. They may also reasonably value a unit’s layout, parking, outdoor space, school access, or commute in ways an absentee investor would not. Rental income can help support the purchase, but lender treatment of projected or existing rent varies by borrower profile and loan program.
The trade-off is that an owner-occupant should not rely on a future vacancy or move-in plan without understanding the current lease, local rules, and notice requirements. In a tenant-protective jurisdiction, possession is not simply a matter of buying the building. A well-written offer and a thorough review of tenancy records are essential.
Pure investment purchases require a stricter income lens
For an investor, the question is not whether the duplex could rent for an attractive amount someday. The question is what income is legally and practically available during the ownership period. A building with long-term tenants paying below current market rent may still be a sound acquisition, particularly in a strong location, but the buyer should price that reality into the offer.
Projected rents should be supported by comparable rentals with similar condition, unit size, parking, laundry, outdoor access, and utility arrangements. A remodeled two-bedroom in Burlingame or San Mateo does not automatically set the rent for an older unit with limited storage or no dedicated parking.
How to underwrite a duplex beyond the listing numbers
Listing income and expense figures are a starting point, not a conclusion. A careful underwriting process separates documented operating performance from assumptions.
Begin with actual leases, rent rolls, security-deposit records, payment history, and utility bills. Confirm which expenses are paid by the owner and which are paid by tenants. Water, garbage, common-area electricity, landscaping, pest control, and insurance can materially affect a small property’s net income because there are only two units over which to spread costs.
Then account for vacancy, repairs, capital improvements, and management. Even a self-managed duplex requires an owner’s time and reserve funds. A modest repair allowance is not enough if the roof is nearing the end of its life, the sewer lateral needs work, or aging electrical panels will complicate future upgrades.
A useful analysis typically looks at:
- In-place gross rent and supportable market rent for each unit
- Property taxes after reassessment at the expected purchase price
- Insurance costs, including any earthquake coverage decisions
- Utilities, maintenance, reserves, and property management
- Mortgage payment scenarios at realistic rates and down-payment levels
- The cash required for closing, repairs, and an adequate operating reserve
Property taxes deserve particular attention. California’s Proposition 13 framework can make a seller’s current tax bill look unusually low relative to what a buyer will pay after a sale. Underwriting based on the seller’s assessment rather than the anticipated reassessed value can create an immediate shortfall.
Tenant rules are part of the asset
In the Bay Area, a duplex is not only a building. It is also a set of contractual relationships and local regulatory obligations. San Francisco, for example, has extensive rent and eviction protections, while other cities and counties may have their own ordinances. Rules can differ based on construction date, unit type, tenancy history, owner occupancy, and the nature of any proposed changes.
Buyers should review leases and amendments, rent-increase history, notices, registration requirements, and any prior disputes or claims. If the seller reports a unit as vacant, confirm when and why it became vacant. If a tenant is month-to-month, avoid assuming that creates unrestricted flexibility.
This review is not an argument against buying tenant-occupied property. Stable tenants can be an advantage, providing documented income and reducing turnover. It is an argument for treating tenancy as a central element of due diligence rather than an afterthought. A real estate attorney or qualified local housing professional can advise on legal questions specific to the property and municipality.
Location still determines the quality of the investment
The Bay Area is not one rental market. Demand patterns vary sharply by neighborhood, commute access, school districts, job centers, walkability, and the available supply of comparable rentals.
In San Francisco, proximity to transit, neighborhood retail, parks, and major employment corridors can affect tenant demand as much as bedroom count. On the Peninsula, well-maintained units near Caltrain, downtown amenities, and major employers may attract renters who value access and convenience. In Palo Alto, Menlo Park, Belmont, San Carlos, and Burlingame, strong household incomes can support higher rents, but acquisition prices may compress immediate returns.
Look beyond the neighborhood name. Evaluate the block, street parking, unit privacy, natural light, stairs, noise exposure, and separation of utilities. A duplex with two clearly independent homes tends to be easier to lease and manage than one with awkward shared circulation or an unclear division of outdoor space.
Physical condition can create either leverage or liability
Older Bay Area duplexes often have character and strong locations, but their systems may be nearing expensive decision points. Inspections should look closely at foundation and seismic considerations, roof condition, drainage, sewer line, plumbing, electrical capacity, heating, windows, and signs of moisture intrusion.
Permits matter as well. Confirm that the unit count, layouts, and major improvements align with public records and permit history. An unpermitted conversion may affect financing, insurance, resale, and the ability to rely on projected rental income. A lower purchase price does not compensate for every compliance issue.
There can be opportunity in a property that needs thoughtful improvement. Updating kitchens, baths, lighting, landscaping, or laundry can strengthen tenant appeal. However, renovation assumptions should include realistic timing, tenant access, permitting, and carrying costs. Improvements that make sense in a vacant unit may be impractical in an occupied one.
Make the offer reflect certainty, not optimism
Competitive Bay Area properties often attract buyers who can move quickly. Speed should come from preparation, not from skipping analysis. Obtain lender guidance early, understand your cash position, and establish investment criteria before the right property appears.
When a duplex has complicated tenancy, deferred maintenance, or uncertain income, the offer should reflect that risk. A clean offer with credible financing can be compelling, but it should not require the buyer to accept unsupported rent projections or vague disclosures. Clear due diligence questions early in the process can prevent expensive surprises later.
Parc Bay Real Estate approaches investment acquisitions with the same disciplined attention applied to high-stakes residential purchases: assess the property’s present reality, identify its future options, and negotiate from a well-supported position.
The best duplex is not necessarily the one with the highest advertised rent or the most dramatic projected appreciation. It is the property whose income, condition, tenancy, and location fit your capital plan well enough that you can own it confidently through changing market cycles.