Buying a first home in Burlingame is easier to navigate when every decision has a purpose: understand your borrowing range, compare homes with clear priorities, and protect your timeline through inspections and closing. This guide breaks the process into practical milestones so you can move from preapproval to keys with a calmer, more informed plan.
Start With a Lending Plan, Not a Listing Feed
It is tempting to begin with photos, open houses, and a mental wish list. Before falling in love with a particular property, however, build a financing plan that gives your search useful boundaries. In Burlingame and throughout the Peninsula, homes can vary widely by location, condition, lot size, and property type. Knowing how those differences connect to your budget helps you evaluate opportunities quickly when the right one appears.
Preapproval is the working foundation. A lender reviews income, assets, credit, debts, and loan-program requirements to estimate the amount and terms you may qualify for. A preapproval letter is more useful than a quick online estimate because it identifies documentation early and signals that a lender has completed an initial review. Ask about the interest rate assumptions, estimated closing costs, down-payment options, mortgage insurance where applicable, and how long the preapproval remains valid.
Your comfortable monthly payment may be different from the maximum amount a lender approves. Create a personal spending plan that accounts for principal and interest, property taxes, insurance, possible homeowners association dues, utilities, maintenance, and savings goals. For a condominium, review the monthly HOA fee and ask what it covers. For a detached home, leave room for seasonal upkeep and future repairs. This is not about limiting the search; it is about choosing a price range that supports your larger financial picture.
A strong preapproval includes more than a purchase-price number: it should help you estimate cash needed for the down payment, inspections, appraisal, lender fees, title costs, and prepaid items before closing.
Gathering documents before you need them can reduce friction later. Recent pay stubs, bank and investment statements, tax returns, identification, and explanations for large deposits are commonly requested. If your financial picture includes self-employment income, stock compensation, a recent job change, or funds from multiple accounts, discuss those details with a lender at the beginning rather than during contract deadlines.
Build a Search Strategy Around Daily Use
Once your price range is established, turn broad preferences into a ranking system. Burlingame offers a mix of residential streets, condominium communities, access to parks and trails, village-center amenities, transit options, and connections to nearby Peninsula employment centers. Instead of trying to find a home that checks every box, identify the features that affect your day-to-day experience most: layout, parking, outdoor space, storage, work areas, transit access, or proximity to the places you visit regularly.
It also helps to separate needs from improvements. A home may have the right location and floor plan but need cosmetic updates. Another may be polished but offer less flexibility in the layout. Look beyond staging by asking how the rooms function, where light enters during the day, what storage is actually available, and whether the property’s condition matches its price and your renovation tolerance.
When touring, take consistent notes and photos where permitted. Record practical details that blur together after several showings: street activity at the time of visit, laundry setup, electrical panel information, apparent drainage, closet dimensions, parking configuration, and visible deferred maintenance. Reviewing these observations alongside disclosures helps turn an emotional first impression into a more complete comparison.
Read the Property Before Writing an Offer
In a competitive market, preparation is often what creates confidence. California transactions may include seller disclosures, preliminary title information, inspection reports, permit records, HOA documents for applicable properties, and other material for review. These documents can reveal important details about the home’s history, maintenance, ownership costs, and potential questions to investigate further.
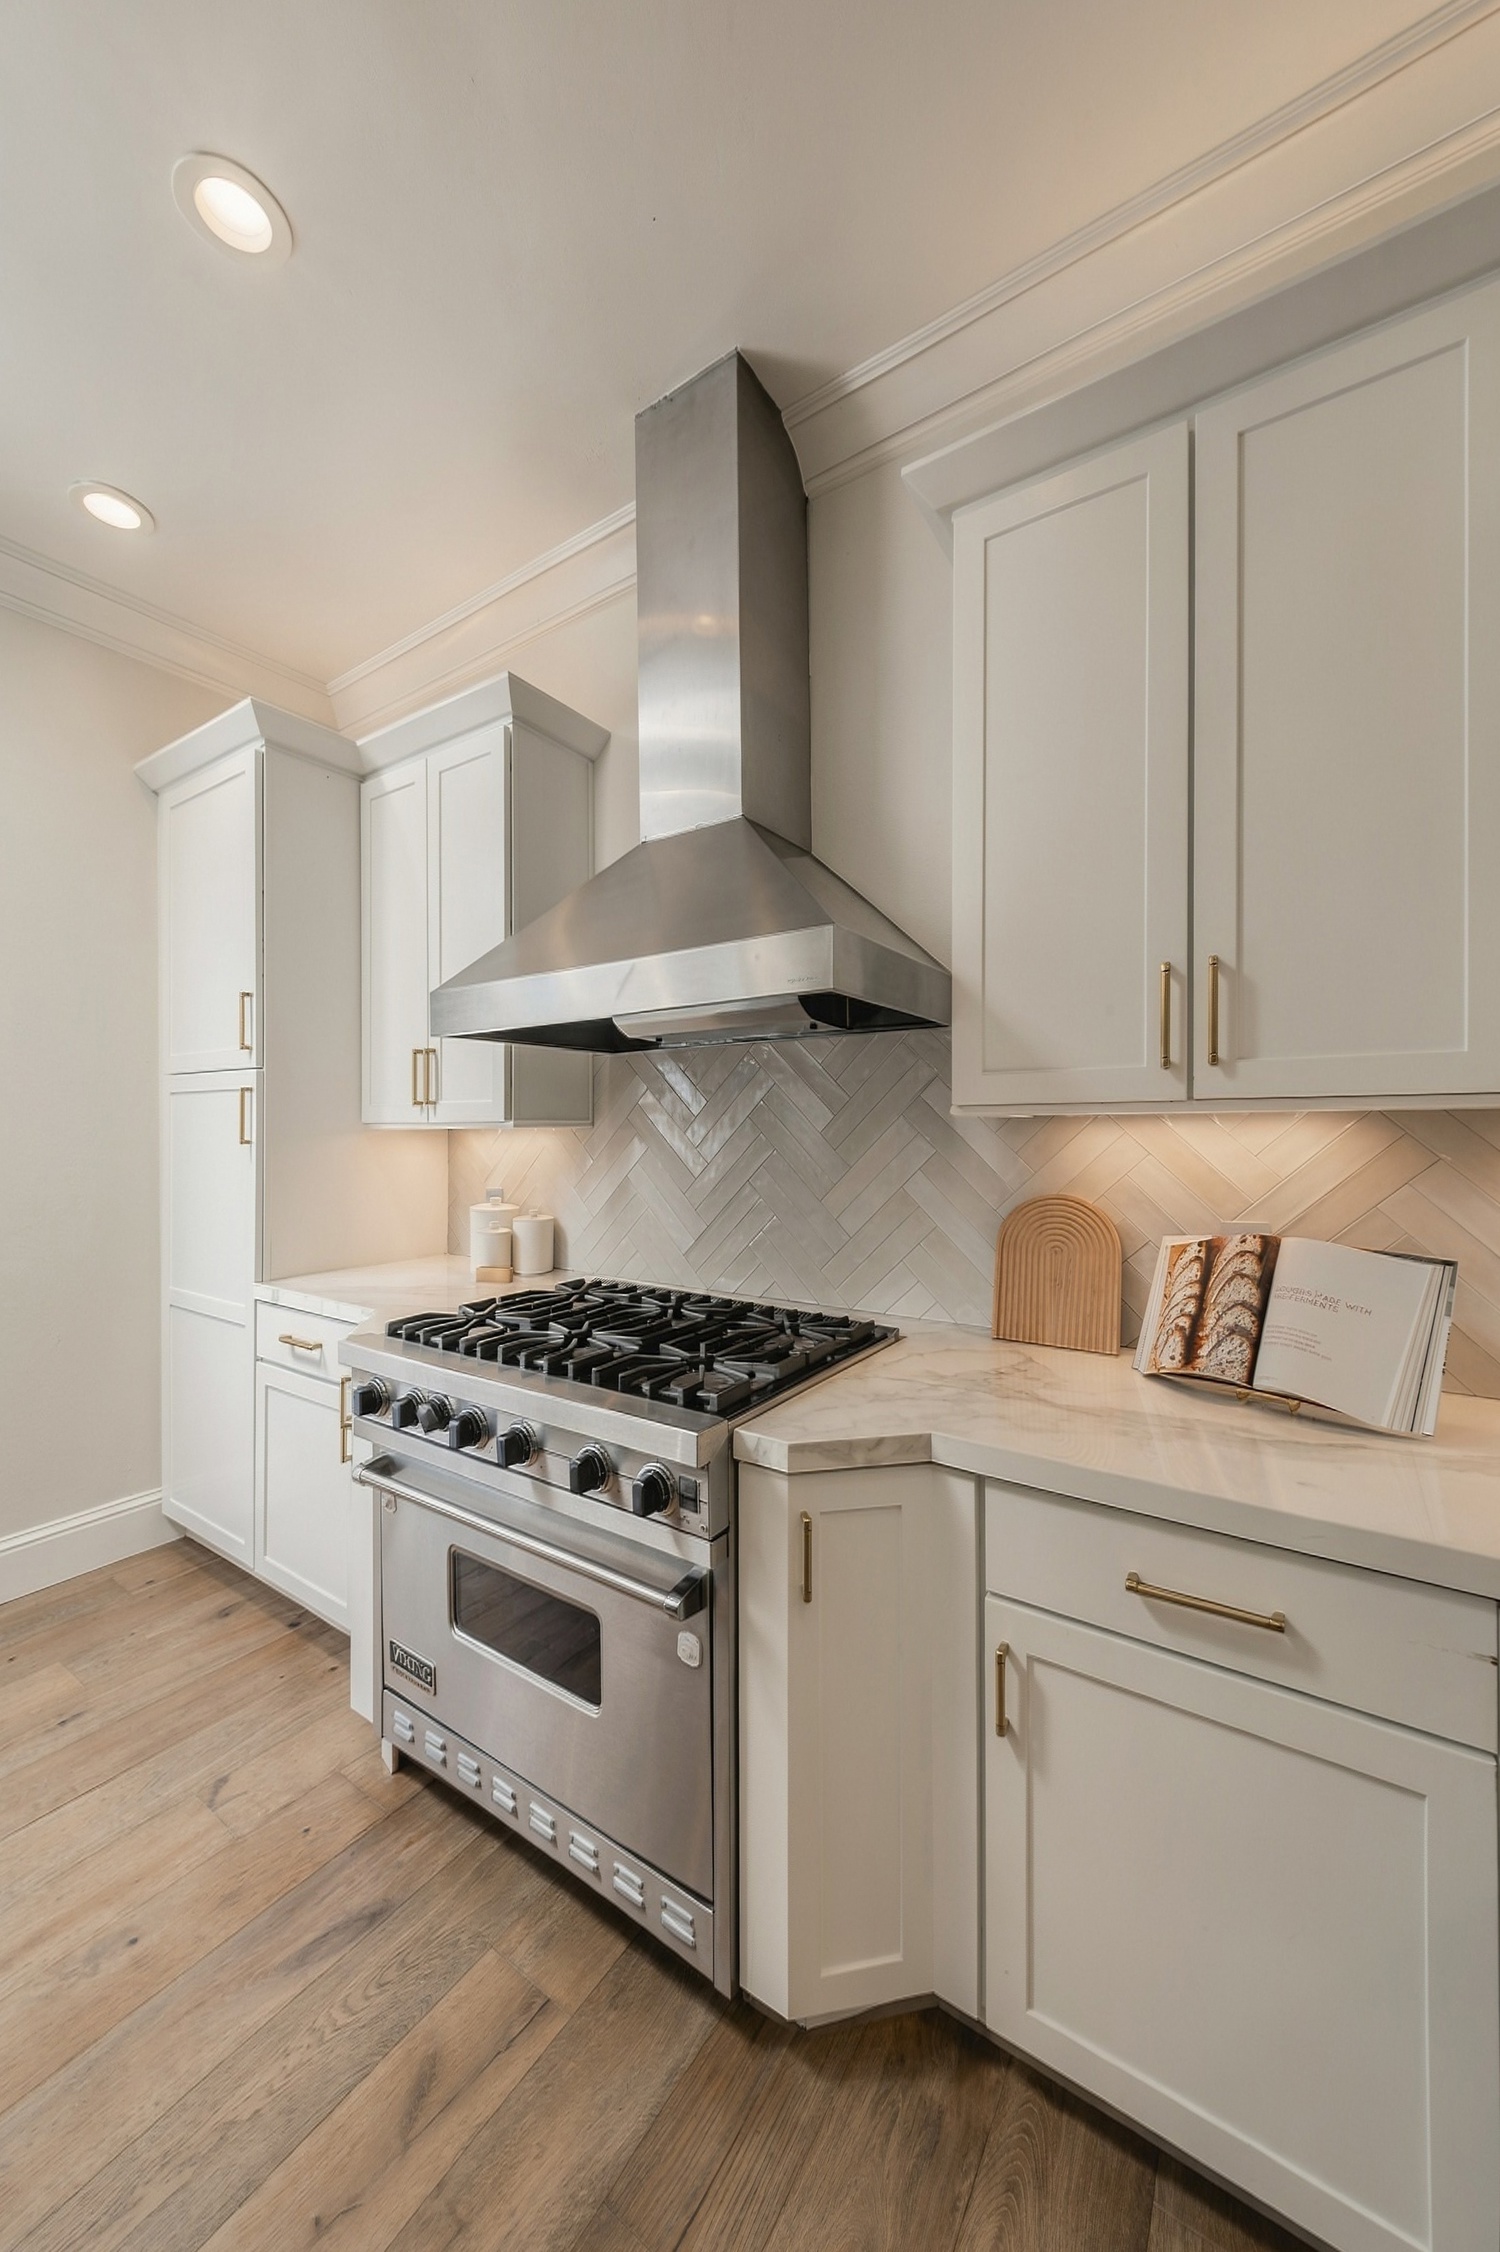
Pay particular attention to items that influence long-term ownership. For a detached home, those may include roofing, drainage, foundations, heating systems, electrical service, plumbing, trees, and any visible signs of water intrusion. For a condominium or townhome, review HOA financials, meeting minutes, reserve information, insurance coverage, governing documents, and any planned assessments. When a report raises a question, a qualified inspector or specialist can help you understand the scope and likely cost of the issue.
An offer is more than a price. It can include the deposit amount, proposed closing date, financing terms, requested contingencies, and personal-property details. The strongest structure depends on the property, your financing, the seller’s timeline, and what you have learned through due diligence. A clear offer that reflects your actual comfort level is more valuable than an aggressive one that creates avoidable pressure after acceptance.
Keep enough financial flexibility for the period after closing. Even a carefully maintained home can bring immediate purchases: window coverings, tools, moving services, furnishings, appliance adjustments, or a repair that was not urgent enough to renegotiate. A reserve fund gives you options and can make the transition into ownership feel much more manageable.
Before removing any contingency, confirm that you understand the relevant reports, lender conditions, and repair implications. A quick question asked before a deadline can prevent a rushed decision later.
From Accepted Offer to Closing Day
After acceptance, the timeline becomes more detailed. Your lender proceeds with underwriting and orders an appraisal, while the escrow and title teams coordinate documents, deposits, title review, and closing requirements. The appraisal is an opinion of value prepared for the lender; it is not a replacement for inspections or your own evaluation of the property’s condition and fit.
During this stage, respond promptly to requests from your lender and escrow officer. Avoid opening new credit accounts, making unusually large purchases, moving money between accounts without documentation, or changing employment arrangements without first discussing the potential impact with your lender. Even positive financial changes can require additional review when a loan is nearing final approval.
Near closing, you will review final loan disclosures and arrange the required funds according to escrow instructions. Always verify wire instructions directly through a trusted phone number before sending money; wire fraud is a serious risk in real estate transactions. A final walkthrough is typically an opportunity to confirm that the property is in the agreed condition, included items remain, and any negotiated work has been addressed as documented.
Closing day is not the finish line for preparation; it is the start of ownership. Save copies of your closing documents, service records, warranties, inspection reports, and improvement receipts in one secure place. Establishing a maintenance calendar for systems such as heating, gutters, landscaping, and smoke or carbon monoxide detectors can protect both comfort and long-term value.
Talk through your home-buying plan
A Clear Process Creates Better Decisions
First-time buyers do not need to know every answer before beginning. They need a thoughtful sequence: define the budget, understand the local inventory, investigate each property, write an offer that fits the facts, and stay organized through escrow. With careful preparation and professional guidance, the steps from preapproval to closing become less mysterious and far more actionable.
Burlingame home buying rewards patience, detail, and perspective. Keep your priorities visible, give each document the attention it deserves, and make decisions based on both the home in front of you and the life you want it to support. The result is not simply a successful closing day, but a purchase made with clarity.
Navigating Burlingame's luxury market takes more than access to listings—it takes sharp negotiation and seasoned judgment. Kathy Chan, Founder and Managing Broker of Parc Bay Real Estate, brings over 15 years of experience in luxury buying, leasing, and estate planning across San Francisco and the Peninsula. Known for her analytical command of complex matters and exceptional negotiation skills, Kathy has built a long record of successful transactions and a practice rooted in referrals from Silicon Valley executives, professional athletes, and business elites across Asia. Her approach is simple: clear information, thoughtful preparation, and unwavering advocacy for her clients' best interests.
Talk with Kathy Chan about your Burlingame real estate plans.